The Best Way to Save Money for Kids: Options Explained
Learn the best way to save money for kids, compare savings, custodial, and education accounts, and build an automatic plan that teaches smart habits.
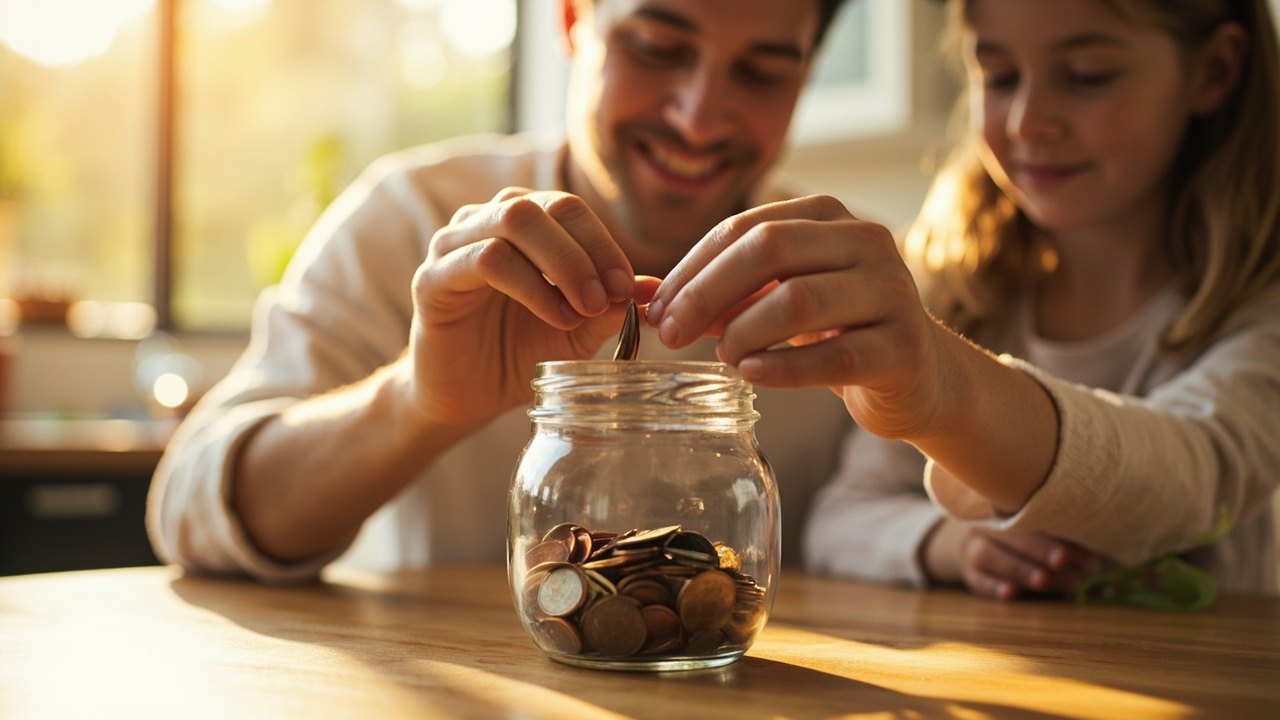
The best way to save money for kids is to use an automatic transfer into a separate savings account, then add tax-advantaged education options when appropriate. Involve your child with small goals, matching contributions, and regular reviews so saving becomes a habit, not just a balance.
The short version
- Open an account in your child’s name or open a dedicated account you manage for the money.
- Automate a manageable transfer after each payday rather than waiting to save what remains.
- Choose a taxable savings account, custodial account, 529 plan, or education savings account based on the goal.
- Give your child a visible goal and a small job, such as matching deposits or completing money tasks.
What is the best way to save money for kids?
The best approach combines a safe place for short-term savings with a longer-term account for education or another major goal, supported by automatic transfers and good habits.
A simple plan works best when it answers three questions: Who controls the money? When can the child use it? What is the money meant to accomplish? A bank or credit union account may fit a near-term goal, while a tax-advantaged education account may be more useful for qualified education expenses.
A practical family plan
- Choose one specific goal, such as a first vehicle, a college fund, or spending money for a school trip.
- Select an account that matches the timeline and your family’s tax situation.
- Set an automatic transfer you can sustain without borrowing from another bill.
- Show your child the balance and explain what each deposit is for.
- Review the plan every few months and increase contributions when your budget allows.
Families with different priorities do not need identical accounts. A dedicated savings account may be enough today, while another family may benefit from a custodial account or education plan. This is general information, not financial advice; rules vary by state and account type, so consult a qualified financial professional when the choice is substantial.
Which savings account is best for a child?
For many families, the best way to save money for kids is to match the account to the purpose of the money and the age of the child, rather than choosing based on a headline feature.
Minor savings accounts
A minor savings account is usually opened by a parent or guardian for a child. The child may receive a debit card, online access, or both, depending on the institution and the account terms. This makes it useful for teaching everyday money management, buying books, saving for a hobby, or building a small emergency cushion.
Look for a low-fee account, easy parental controls, and a clear process for transferring money. If the account earns interest, it may be taxable. Deposits in bank and credit union accounts are generally covered by federal deposit insurance, subject to its ownership and account rules.
Custodial accounts
A custodial account, such as an UGMA or UTMA, gives a custodian legal responsibility for the child’s money. The custodian must act for the child’s benefit, but money in the account generally belongs to the child. Unlike a standard account opened for a child, it usually gives the child no direct control over withdrawals.
Custodial accounts can accept various investments and may be useful when the money is not reserved for education. However, they can have tax consequences, and money remaining in the account may affect the child’s financial aid eligibility. Gifts above the annual exclusion limit may also trigger gift tax reporting, so larger contributions deserve professional review.
529 plans and other education accounts
A 529 plan is a state-sponsored or state-managed program designed for qualified education expenses. The account owner usually controls contributions and changes the designated beneficiary, though not every beneficiary is eligible for every plan or every expense. Contributions may qualify for a federal or state tax benefit, and qualified earnings are generally exempt from federal income tax when used for qualified expenses.
An education savings account, including a Coverdell ESA, must be used for qualified education expenses and has age and contribution restrictions. It can be a useful complement to a 529 plan when its eligibility and contribution rules fit your family. Compare withdrawal penalties, eligible expenses, fees, state tax treatment, and beneficiary rules before contributing.
| Option | Control and ownership | Best fit | Main watchout |
|---|---|---|---|
| Minor savings account | Parent opens it for the child; access varies | Short-term goals and teaching | Interest may be taxable |
| Custodial account | Money belongs to the child; custodian manages it | Flexible savings for a child | Tax and financial-aid effects |
| 529 plan | Account owner generally controls it | Long-term education expenses | Only eligible expenses qualify |
| Education savings account | Owner controls it for a designated beneficiary | Qualified education expenses | Age, contribution, and withdrawal rules |
| Coverdell ESA | Owner controls it for a designated beneficiary | Flexible qualified education expenses | Annual contribution limit and eligibility rules |
How much money should you save for your child?
Save an amount your family can add consistently, because regular contributions matter more than choosing an ambitious target you cannot maintain.
A useful starting point is to define the goal and work backward from the likely date and cost. For education, estimate the range of expenses rather than one exact number because prices, aid, and the child’s plans can change. For a smaller goal, choose a date and divide the target into monthly or per-paycheck amounts.
- Write down the goal and target date.
- Separate essential future costs from optional enrichment.
- Choose a first contribution that fits comfortably in your budget.
- Plan for occasional increases, such as after a raise, bonus, or tax refund.
- Review the target annually and adjust it when plans change.
Do not use money needed for current housing, emergencies, debt payments, or retirement savings to fund a child’s account. Your child’s savings should not weaken your household’s financial foundation.
How can you teach your child to save money?
Children learn saving faster when they can see the goal, make choices, and experience the connection between their behavior and the balance.
The best way to save money for kids is to combine their own decisions with a family plan that does not depend on perfect habits. A child who chooses between saving and spending may make different choices each week, so give them a small amount they can genuinely manage.
Simple lessons that work
- Divide money into spending, saving, and giving categories.
- Let your child compare prices before buying something.
- Match a portion of deposits your child makes from chores or gifts.
- Set a visible savings goal with a picture and a target date.
- Celebrate reaching milestones without turning saving into a competition.
Keep the lesson age-appropriate. Younger children can sort coins and watch a balance grow, while teenagers can compare account terms, create a budget, and track progress. Avoid making savings a punishment or insisting that every gift must be saved.
What do you need to open a savings account for a child?
You will generally need your child’s identifying information, your own identification, an initial deposit, and the tax or beneficiary information required for the selected account.
Institutions may request additional documents, and requirements can differ for custodial accounts, 529 plans, and education savings accounts. Ask the provider what information is needed before visiting. If you are opening an account for a child who does not yet have a Social Security number, ask what alternatives the institution allows.
Also request the fee schedule, withdrawal rules, minimum-balance requirements, tax reporting details, and information about parental access. For an education plan, confirm the state or program rules, eligible expenses, and beneficiary options. Keep the account information, statements, and tax documents together so annual reporting is easier.
How can you automate saving for your child?
Automation makes saving dependable because money moves on a schedule before you have a chance to spend it.
- Choose a transfer amount that will not disrupt your essential budget.
- Schedule it for the day after payday, when income is most likely to be available.
- Connect transfers from a checking account rather than a credit card.
- Name the transfer or account so you can identify it in your records.
- Check the first few transfers and review them periodically.
You may be able to automate this through your bank’s website, mobile app, bill-pay service, or by calling the institution. Menus vary by device, bank, and account, but you will generally look for a transfers, payments, or automatic transfer area. Set the amount, frequency, start date, and destination account.
Automation is not a substitute for oversight. Review automatic deposits, waived fees, and canceled transfers. If your income or expenses change, adjust the amount rather than allowing an account to go dormant or overdrawing another account.
Common mistakes to avoid
The most common mistake is choosing a complicated account before deciding what the money is for.
- Starting with no goal: A specific purpose makes tradeoffs easier and progress visible.
- Leaving the account inactive: Review it periodically and confirm that automatic transfers continue.
- Ignoring fees and restrictions: Read withdrawal, minimum-balance, contribution, and beneficiary rules before opening.
- Saving without teaching: Explain the balance, the goal, and the reason for each contribution.
- Putting too much money in one account: Keep short-term savings separate from long-term education money.
- Missing annual tax steps: Save statements and confirm any required forms or beneficiary updates.
Frequently asked questions
Families often have practical questions about account access, taxes, and how to begin, and clear answers can prevent expensive misunderstandings.
Can a child open a savings account on their own?
A minor often needs a parent, guardian, or other adult involved in opening an account, although some institutions allow teenagers to manage certain accounts. Requirements depend on the institution and the child’s age, so ask what forms and adult participation are required.
Should I save for my child in my name or theirs?
An account in your name gives you control and may be more flexible, while a custodial account legally belongs to the child. An education plan lets an owner designate a beneficiary, but its withdrawals remain subject to eligible-expense rules.
Are custodial accounts better than 529 plans for education?
They serve different purposes. A 529 plan is designed for qualified education expenses and may offer tax advantages, while a custodial account is flexible but can create tax and financial-aid considerations. Compare the child’s age, the intended expenses, and your tax situation.
How often should I contribute to my child’s account?
Consistency usually matters more than the exact schedule. Many families automate a transfer after payday and adjust the amount when their finances change. For a child learning to save, occasional hands-on deposits can supplement the automatic transfer.
Start today by writing down one goal, choosing the matching account, and scheduling the first transfer you can comfortably repeat; then show your child the plan and celebrate the first balance together.